
A conventional debt plan often begins with a reassuring sentence: pay the same extra amount every month. That works when income arrives in roughly the same shape every month. It becomes fragile when earnings depend on shifts, commissions, contracts, harvests, tips, seasonal demand or invoices that do not respect the calendar.
In an uneven-income household, a strong month can make an ambitious payment look permanent. A quiet month then forces the same household to borrow for groceries, miss another bill or pull money back onto a card. The debt balance falls briefly, but the system around it becomes less stable.
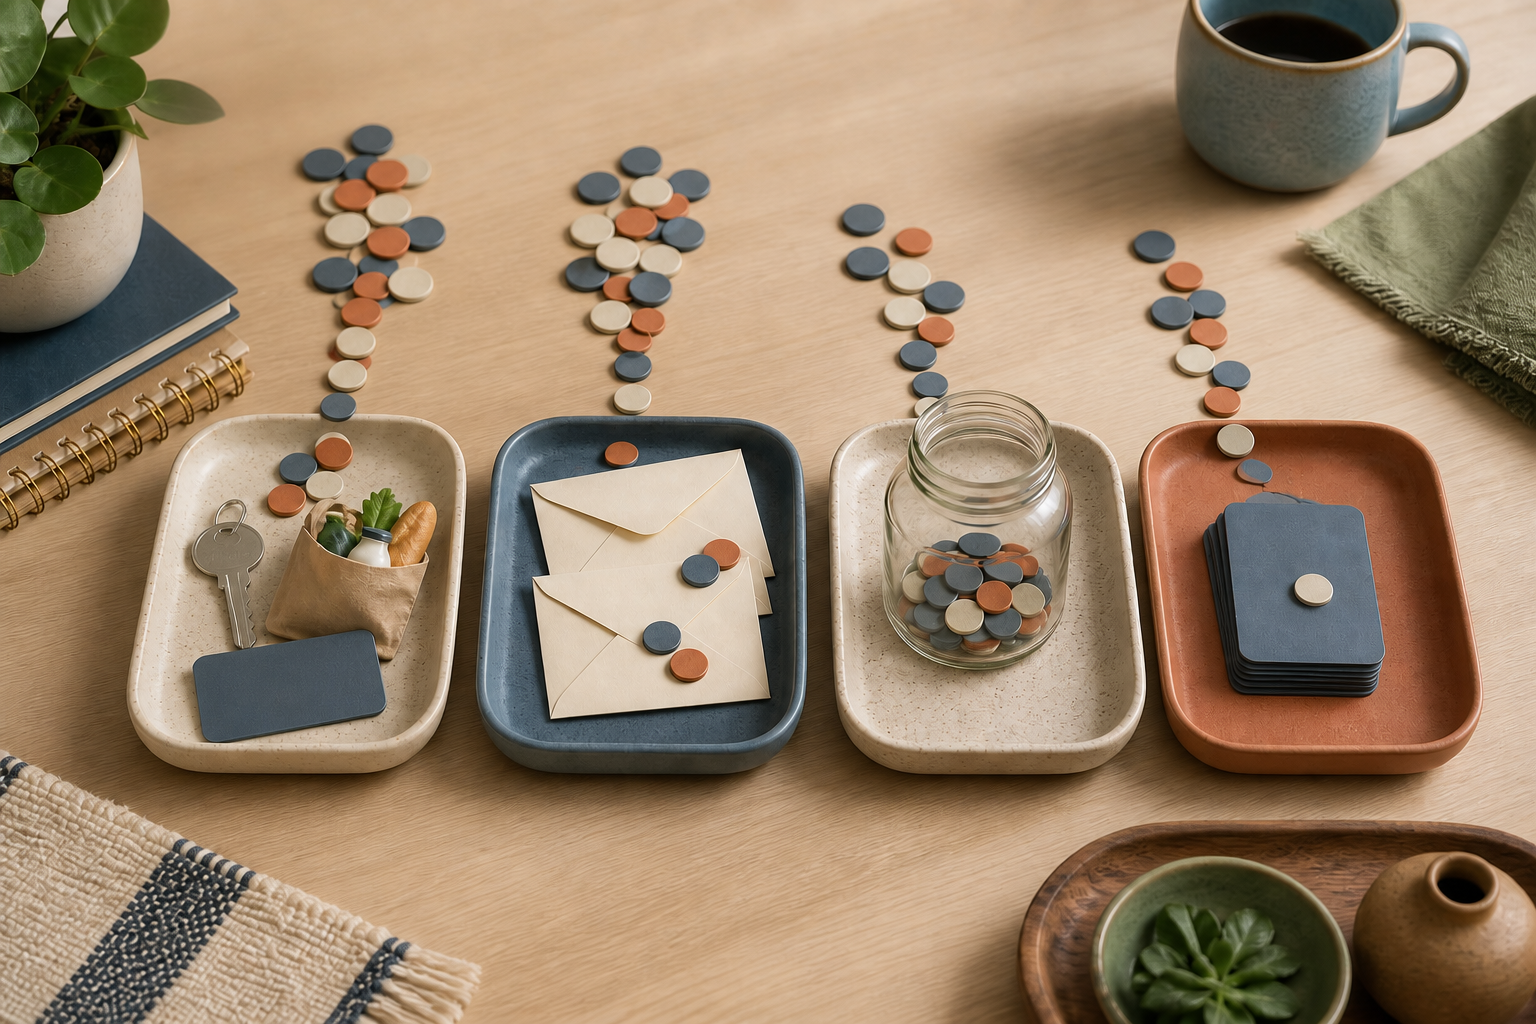
A debt payoff waterfall for irregular income solves a different problem from a fixed repayment schedule. It does not predict exactly how much extra money will appear. It decides the order in which money will be used whenever it appears. That order protects the household first, honors required commitments, creates a small shock absorber and only then accelerates a chosen balance.
This is a planning framework, not individualized financial, legal or tax advice. Contracts, collection rules, benefits and relief options vary by lender and jurisdiction. The useful idea is the sequence: decide the consequences before deciding which balance deserves the next dollar.
Why an average month can be a dangerous foundation
Suppose twelve months of income add up to a comfortable annual number. Dividing that number by twelve produces a clean monthly average, but the household never actually receives the average. It receives a weak January, a busy March, a delayed May invoice and an unusually strong October. Bills arrive during the valleys as reliably as they arrive during the peaks.
An average can therefore describe the year while failing to fund a particular Tuesday. Debt trouble is often a timing problem before it becomes a total-income problem. The money may be earned eventually, yet rent, transport, insurance and minimum payments cannot always wait for eventually.
Build the waterfall around a conservative income floor instead. Review a meaningful stretch of real deposits, remove one-off windfalls and identify what a weak but ordinary period looks like. Do not automatically choose the single worst month if it came from an exceptional shutdown, but do not let a record month set the standard either. The floor should be an amount the plan can survive more often than not.
Separate the cash calendar from the debt list
A debt list answers “what is owed?” A cash calendar answers “what must be paid, and when?” An irregular-income plan needs both because balances alone hide timing.
For each debt, record the current balance, interest rate or pricing method, required payment, due date, whether the rate can change, and what happens after a missed payment. Also record any annual fees, promotional-rate expiration dates and collateral attached to the agreement. A car loan and an unsecured card balance may have similar totals but very different consequences if they fall behind.
Then place expected income windows and essential expenses on a calendar. Use ranges where certainty is false. An invoice expected between the tenth and twentieth is not income available on the tenth. Mark it as pending until it clears. The purpose is not to create a beautiful forecast; it is to expose the days on which the account is most vulnerable.
Layer one: protect the ability to live and earn
The first layer receives money for immediate essentials and the costs that allow income to continue. That commonly includes housing, basic food, utilities, necessary medicine, insurance and essential transport. For a self-employed person, it may also include a modest amount for the tools, connectivity, materials or taxes required to keep operating.
This layer comes first because a debt plan that destabilizes housing, health or the ability to work can create larger costs. The order within essentials still depends on circumstances. A household facing a shutoff notice, loss of required insurance or a serious housing deadline should assess the actual consequence and date rather than follow a generic list.
Set an essentials amount for the next pay interval, not an imaginary perfect month. If deposits arrive weekly, fund the next week or two. If projects pay unpredictably, a longer operating runway may be necessary. Keep the boundary clear: convenience and comfort can matter, but they should not quietly enter the protected layer just because a good month makes them affordable.
Layer two: keep required commitments visible
After near-term essentials are covered, fund required debt payments and other time-sensitive obligations. The goal is to prevent an aggressive payment to one balance from causing a preventable delinquency elsewhere.
Do not assume every obligation has the same consequence. A missed secured payment can put an essential asset at risk. Certain tax, court, support or government obligations may follow rules unlike ordinary consumer credit. Promotional financing may become expensive under terms that are easy to overlook. When money cannot cover everything, examine deadlines, contractual consequences and local protections, then contact the relevant provider or a qualified adviser promptly.
Contacting a lender before a missed payment does not guarantee relief, but it can reveal options that are unavailable or harder to arrange later. Ask what a proposed change does to the payment amount, interest, fees, term and credit reporting. Get important terms in durable form. A smaller payment can create breathing room while increasing total cost, so “lower” and “cheaper” are not synonyms.
Layer three: build a small interruption buffer
Sending every spare unit of cash to debt can feel efficient. With irregular income, it can also force the next surprise straight back onto credit. A small, accessible buffer sits between a minor shock and a new balance.
This is not necessarily a fully funded long-term emergency reserve before any extra repayment begins. It is a practical first barrier: enough to absorb a routine gap such as a delayed invoice, modest repair, prescription or unusually quiet week. Choose an initial target tied to real volatility rather than a slogan. Someone paid weekly may need a different first buffer from someone whose clients routinely pay thirty days late.
Define what the buffer is for and where it lives. If it is mixed into everyday spending, a busy month can consume it without a conscious decision. If it is inaccessible when a genuine disruption occurs, it cannot perform its job. After using it, temporarily direct part of the next surplus back to restoration before resuming maximum acceleration.
Layer four: direct the true surplus at one target
Only after the earlier layers are funded does the remaining amount become a true payoff surplus. Directing that surplus to one chosen target creates visible progress without pretending that the same amount will exist next month.
Several targeting rules are reasonable, and each solves a different problem:
- Highest effective cost: Prioritizing the balance with the highest interest and unavoidable fees can reduce total borrowing cost when all other factors are equal.
- Smallest removable payment: Clearing a small balance can release a required monthly payment, which may be valuable when income is volatile.
- Highest consequence: A balance linked to an essential asset, expiring term or rapidly changing cost may deserve attention even when its stated rate is not the highest.
- Most behaviorally useful win: A visible early result can help some people continue, provided it does not ignore an urgent or dangerous obligation.
Choose the rule deliberately and write down why it fits. Reconsider it when rates, employment, household needs or account status change. Constantly switching targets because each new balance feels urgent scatters the surplus and makes the plan hard to evaluate.
Give every deposit the same sequence
The waterfall works best at the moment income clears, not at the end of a month after spending has already expanded. Each deposit passes through the same questions:
- What essentials must be funded before the next likely deposit?
- Which required payments or deadlines arrive in that interval?
- Is the interruption buffer at its current target?
- What amount is now genuinely available for the selected debt?
A separate holding account or labeled budgeting buckets can make the sequence easier to see, but the method does not depend on a particular app. The important control is that money assigned to tax, rent or a required payment does not appear available for extra debt reduction.
For very small deposits, the entire amount may remain in the first two layers. That is not a failed payoff month. It is the plan preventing one debt payment from creating another emergency. A stronger deposit will move farther through the waterfall.
Use rules for peaks before they arrive
Good months create their own risk. After a long lean period, a large payment can feel like permission to repair every neglected category at once. Some catch-up spending may be necessary, but decisions made in the excitement of a peak often recreate the shortage.
Set a surplus rule in advance. For example, after current essentials and required commitments are funded, an incoming peak might restore the buffer, reserve for known irregular costs and send the rest to the target balance. The percentages or amounts should reflect the household, not a universal formula. What matters is that the allocation exists before the money creates competing stories.
Windfalls also deserve a pause. Confirm that the amount is final, that tax or business obligations are accounted for and that no near-term essential has been deferred. Then run it through the same waterfall. Treating exceptional income as exempt from the system weakens the very months that could create durable progress.
An illustrative irregular-income month
Imagine a freelancer who begins the month with a modest buffer and three debts. Deposits of 900, 650 and 1,400 arrive at uneven intervals. The first deposit funds food, transport and the utility bill until the next expected payment. It also reserves a required loan payment due before then. Nothing reaches the target debt.
The second deposit arrives later than expected. It covers the next essential interval and two minimum payments. A small amount restores money used from the buffer during the delay. Again, there is no dramatic payoff.
The third deposit clears after the essential and required layers for the rest of the month are already funded. The buffer reaches its chosen level, known tax money is separated and the true remainder goes to the selected high-cost balance. The extra payment is not the same as last month’s and is not promised for next month. It is still meaningful because it did not borrow stability from another category.
The example illustrates the central tradeoff: progress may look uneven on a chart while being more durable in real life.
Measure whether the system is improving
A falling total balance matters, but it is not the only sign of progress. Review the plan over several income cycles and ask:
- Were required payments made without new borrowing for essentials?
- Did the buffer prevent a routine disruption from becoming debt?
- Did fees or interest behave as expected?
- Was the target balance reduced, and did its required payment eventually disappear?
- Did pending income repeatedly arrive later than forecast?
- Are essential costs or income floors based on current evidence?
If the plan repeatedly fails before layer four, the answer may not be more discipline. The income floor may be overstated, essential costs may be incomplete or required payments may exceed what the current cash flow can support. That is a signal to explore legitimate hardship options, income changes, cost reductions or qualified counseling rather than hiding the gap with another optimistic forecast.
Know when a simple waterfall is not enough
Pause before paying a balance that may not be yours, is stated incorrectly or comes through a suspicious collection approach. Verify the creditor, amount and account through trusted records. Legal deadlines, disputes and limitation periods vary; a casual payment or acknowledgement can have consequences in some places, so obtain appropriate local guidance when status is unclear.
Urgent professional help may also be warranted when housing or essential property is at risk, court papers arrive, taxes or support obligations are involved, collectors threaten action, or the household cannot cover basic needs. A nonprofit counselor, licensed attorney, regulated insolvency professional or relevant public service may offer options a general framework cannot assess.
Be cautious with anyone who guarantees fast forgiveness, demands an upfront payment for a promised result, discourages communication with creditors or tells a person to stop payments without explaining the consequences. Debt settlement can involve fees, growing balances, credit damage, collection activity, taxes and creditors who decline to participate. A polished promise does not remove those risks.
A plan for sequence, not perfection
Irregular income does not make debt reduction impossible. It makes false precision expensive. The household may not know the size of next month’s extra payment, but it can know what that payment must protect before it attacks a balance.
The debt payoff waterfall turns that principle into a repeatable order: fund the near-term essentials that keep life and income functioning, address required commitments according to consequence, maintain a practical interruption buffer and direct the genuine surplus to one deliberate target. Review the assumptions as reality changes.
The result will rarely be a straight line. Strong months will create visible drops, quiet months may produce only maintenance, and occasional shocks will refill the upper layers first. That uneven progress is not a defect. It is what a debt plan looks like when it is built around the income that actually arrives.